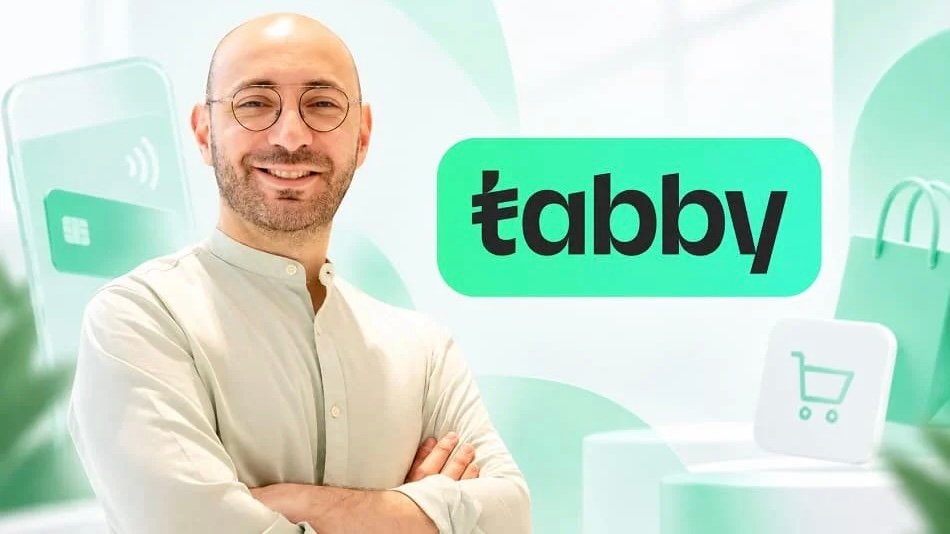
Saudi Arabia-headquartered fintech Tabby has raised $233 million in a Series F equity round, lifting its valuation to $6.5 billion as it expands beyond buy now, pay later into broader financial services. The funding gives the company fresh capital to develop credit and money-management products across Saudi Arabia and the United Arab Emirates.
The round was led by existing investor Blue Pool Capital, a Hong Kong-based investment firm backed by Alibaba co-founder Joe Tsai. Existing shareholders HSG, Wellington Management and Arbor Ventures also participated, showing continued support from investors who have backed Tabby’s growth over several funding stages.
Tabby’s new valuation is a major increase from the $4.5 billion valuation it reached after a secondary share sale in October 2025. It is also nearly double the $3.3 billion valuation attached to the company’s $160 million Series E round in February 2025.
The rise reflects investor confidence in Tabby’s ability to build a broader financial platform. The company began as a buy now, pay later provider, allowing shoppers to divide payments into instalments. It is now seeking to use that customer and merchant network as a foundation for lending, digital money management and other financial products.
The transition is strategically important. Buy now, pay later helped Tabby attract users and merchants, but the service operates within a competitive market. Moving into broader financial services could give the company more ways to generate revenue, deepen customer relationships and increase the frequency with which users interact with its platform.
The company said the new capital will support its next stage of growth in Saudi Arabia and the UAE. Potential products include broader credit, money-management tools and other services designed to help consumers manage payments and spending.
Tabby’s expansion comes as Gulf fintech companies move beyond single-product models. Digital lenders, payment providers and financial apps are increasingly trying to combine payments, credit, savings and account services within one platform. The goal is to become a customer’s primary financial application rather than remain a tool used only for individual purchases.
For Tabby, the opportunity is supported by the scale of its existing network. The company processes more than $18 billion in annualised transaction volume across 25 million users and 70,000 business partners, according to information reported by Traded. Those relationships provide a substantial base for introducing additional services.
A large user base can reduce the cost of launching new products because the company already has customer data, merchant relationships and an established digital interface. However, it also creates responsibility. As Tabby moves into credit and money management, regulators will examine how it assesses borrowers, protects users and handles financial information.
The funding remains subject to customary regulatory approvals, including final clearance from the Saudi Central Bank, known as SAMA. That approval will be important as Tabby expands beyond payments and instalments into activities that may involve more complex lending and financial-service requirements.
Regulation will shape the company’s growth strategy. Consumer-finance providers must manage credit risk carefully, provide clear pricing and ensure customers understand repayment obligations. If Tabby expands into higher-value or longer-term products, its underwriting systems will face greater demands than those associated with smaller instalment purchases.
The company may also target small and medium-sized businesses. Merchant financing and working-capital products could allow Tabby to use transaction data to assess businesses and offer credit based on sales activity. Such products could appeal to merchants that struggle to obtain conventional bank financing.
That opportunity is attractive but carries risk. Small-business income can fluctuate significantly, especially during periods of weaker demand or higher costs. Tabby would need strong risk models and careful monitoring to avoid losses as it expands beyond consumer payments.
The company’s growth also reflects Saudi Arabia’s broader effort to build a digital financial ecosystem. The kingdom is encouraging fintech innovation, increasing access to financial services and supporting technology companies that can serve consumers and businesses through digital channels.
The UAE remains equally important to Tabby’s strategy. The company was founded in the UAE in 2019 and has developed a presence across the Gulf. Operating in both Saudi Arabia and the UAE gives Tabby access to two of the region’s largest and most developed fintech markets.
Those markets have different regulatory requirements and customer behaviours, however. Tabby will need to adapt products, compliance processes and partnerships to each jurisdiction. Cross-border scale can reduce operating costs, but it also increases the complexity of managing licences and consumer-protection rules.
The company’s valuation also places it among the most valuable private fintech businesses in the region. Tabby became the Middle East and North Africa’s first fintech unicorn in 2023, when its valuation exceeded $1.5 billion. The latest round shows how quickly leading regional fintechs can grow when investors see a path toward broader financial services.
The funding market remains selective, making the size of Tabby’s round significant. Investors are increasingly looking for companies with real transaction volumes, established customers and a credible path to profitability. Tabby’s existing network gives it a stronger foundation than an early-stage fintech that has yet to demonstrate user demand.
The company’s expansion will nevertheless increase competition. Banks, digital lenders, payment firms and other fintech platforms are developing similar products across the Gulf. Tabby must maintain customer trust, offer competitive pricing and ensure its services are genuinely useful rather than simply adding more features.
Its buy now, pay later origins may also shape public debate. Regulators and consumer advocates in several markets have questioned whether instalment products can encourage excessive borrowing. As Tabby moves into broader credit, responsible lending and transparent communication will become even more important.
For investors, the main question is whether Tabby can convert its large payment network into a profitable financial-services ecosystem. A high valuation creates strong expectations around growth, product development and risk management. The company must show that its expansion can produce sustainable earnings rather than only increase transaction volume.
For merchants, the broader platform could offer more tools to manage sales, payments and financing. For consumers, it could create a single digital destination for instalments, credit and money management. But those benefits will depend on responsible product design and effective oversight.
The $233 million round therefore marks a strategic turning point. Tabby is no longer presenting itself only as a buy now, pay later company. It is positioning itself as a wider digital financial-services platform for the Gulf, backed by a $6.5 billion valuation and a large regional user base. The next stage will test whether that ambition can be delivered. Tabby must secure regulatory approvals, develop new products, manage credit risk and preserve customer trust as it expands. If successful, the company could become one of the region’s most important independent fintech platforms.